

Run your numbers
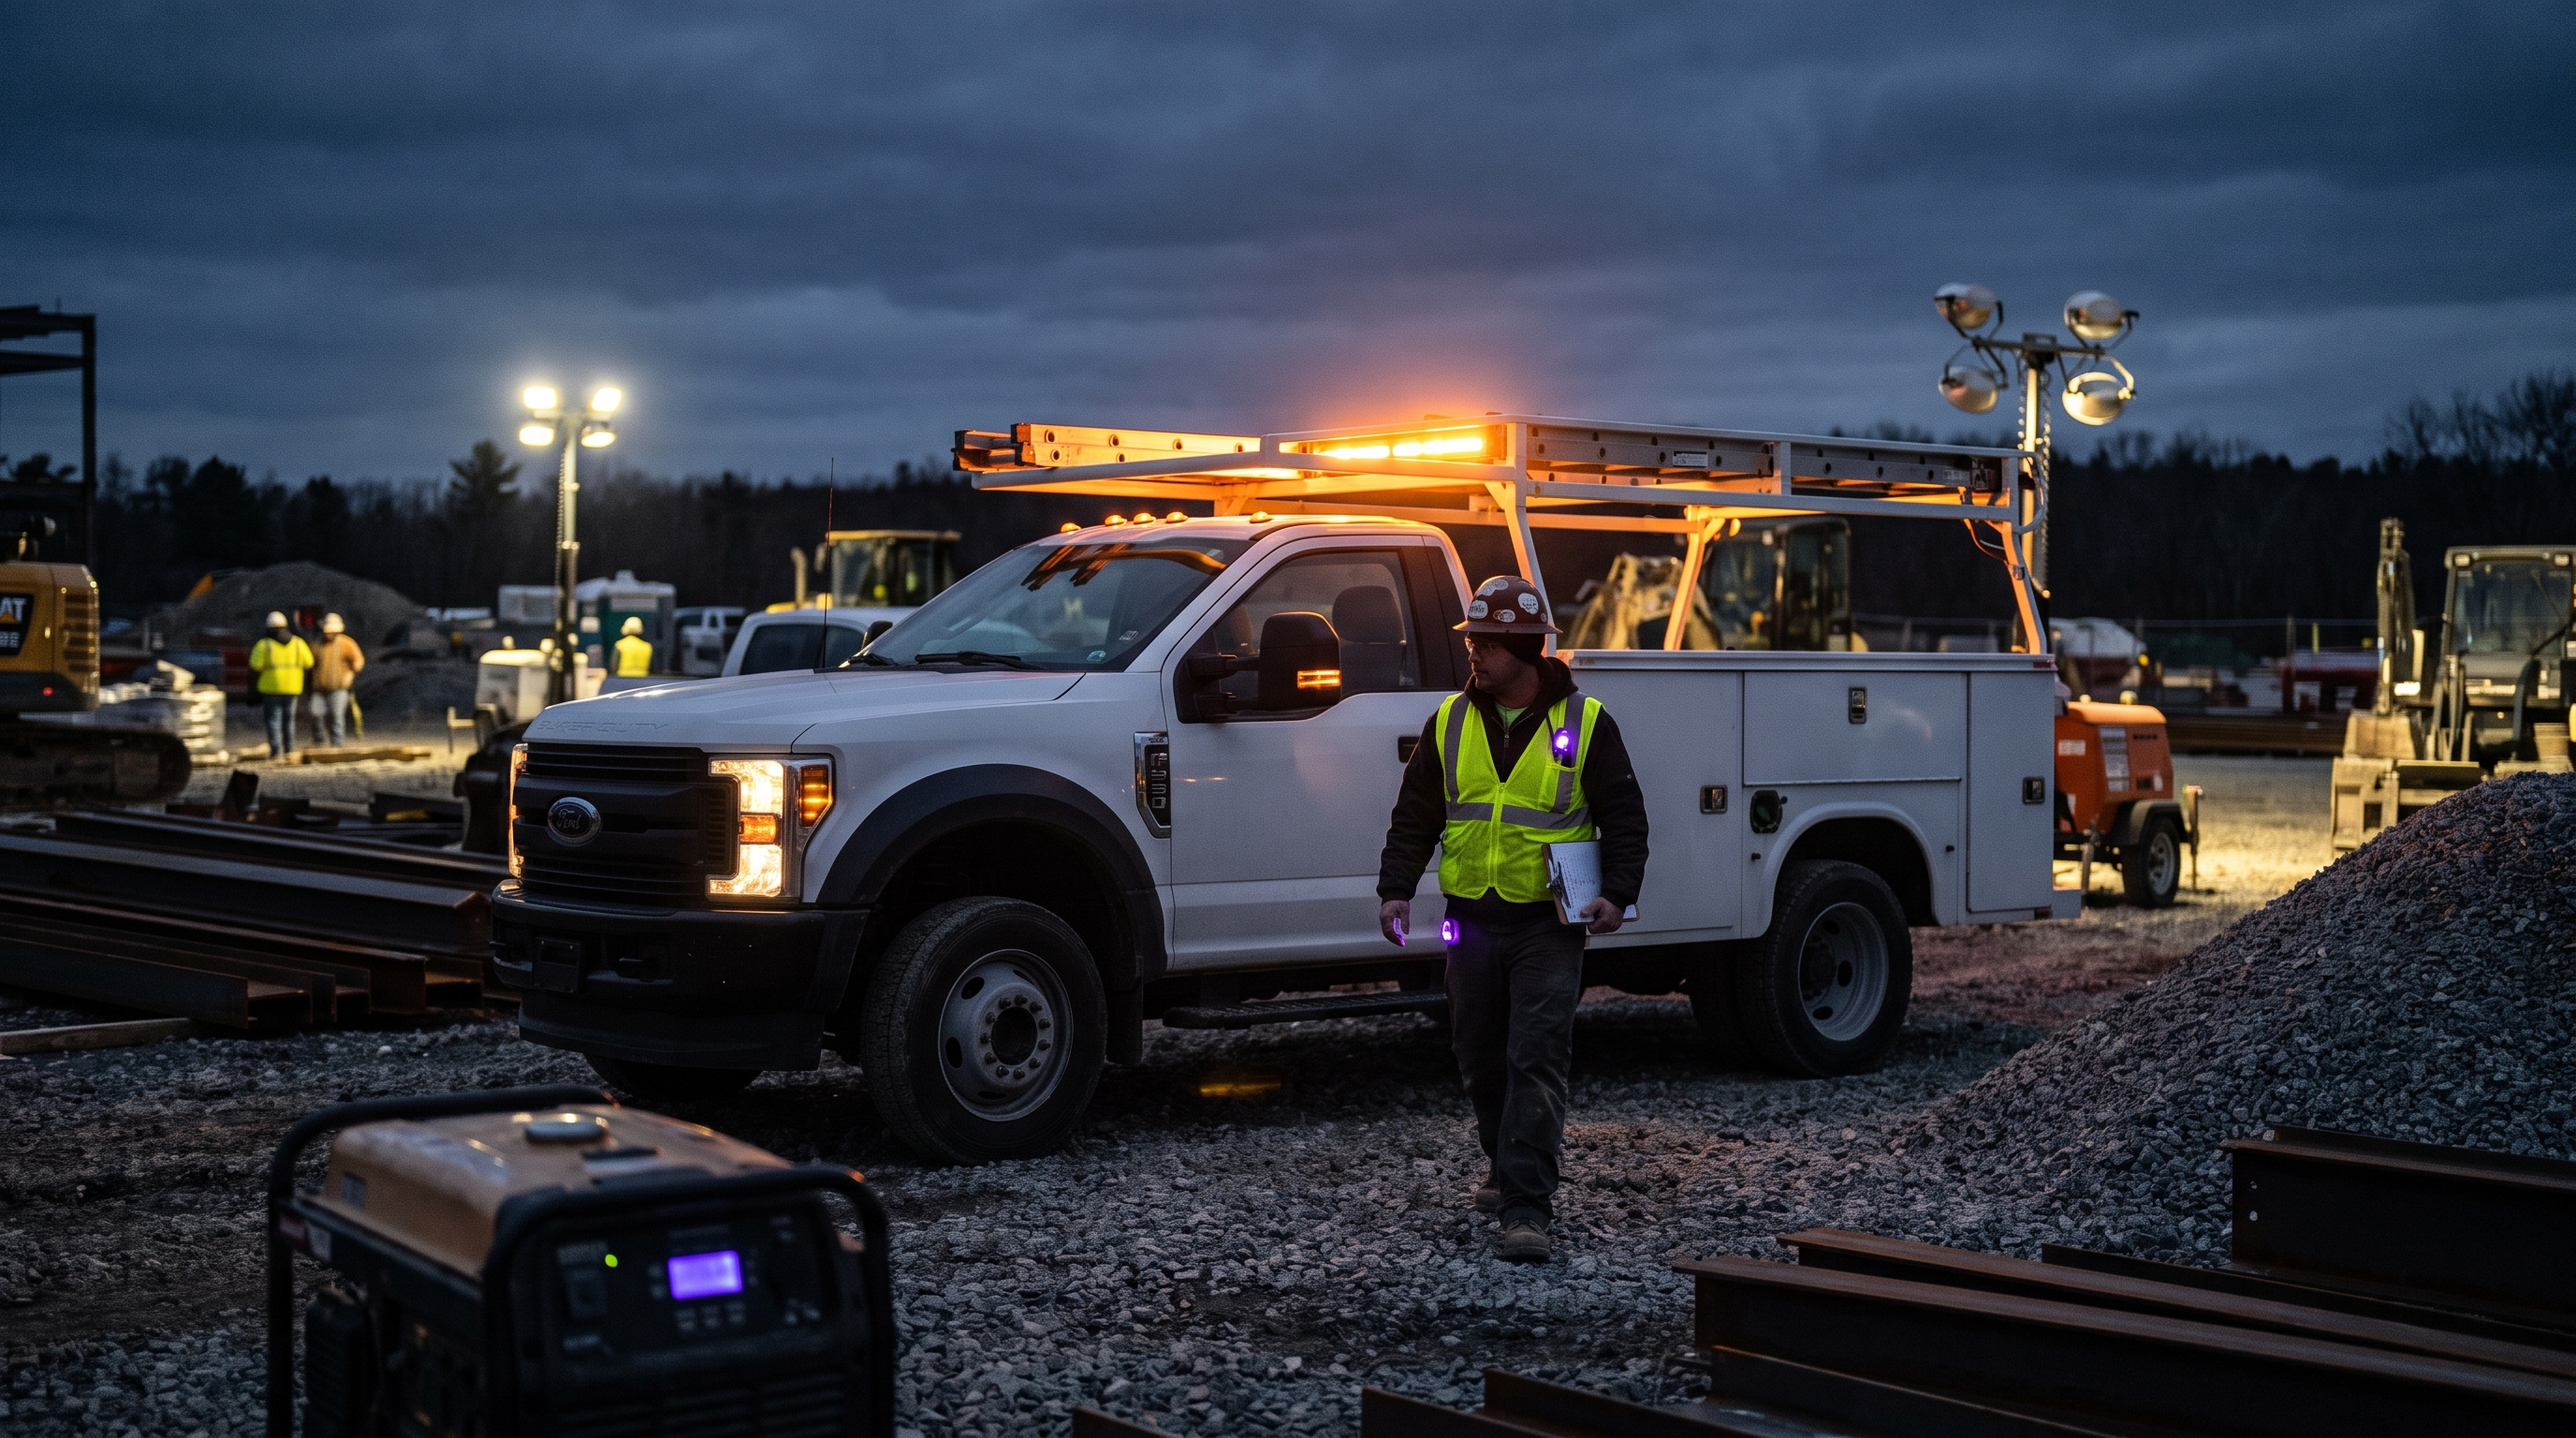
Work trucks and cargo vans aren’t held to the $32,000 SUV cap, so the full business-use basis is deductible in year one.
How Section 179 actually works
Section 179 lets a business deduct the full purchase price of qualifying equipment — including work trucks, cargo vans, and heavy SUVs — in the year it's placed in service, instead of depreciating it over several years. For 2026 the total deduction limit is $2,560,000, the vehicle has to be used more than 50% for business, and it has to be delivered and working by December 31, 2026. Trucks and cargo vans aren't held to the $32,000 heavy-SUV cap. Tom's Ford has been outfitting Monmouth County businesses from Keyport since 1962, and our commercial desk will tell you what a specific unit's GVWR is before you buy — not after.
It's a timing move, not free money.
Section 179 is a deduction, not a credit. It cuts your taxable income, so what you actually save is the deduction multiplied by your rate. A $75,000 deduction at a 35% combined rate is roughly $26,250 in tax — not $75,000 back.
Used counts. Financed counts.
The vehicle has to be new to your business, not new off the truck. Buying it with a loan doesn't change anything — you claim the full price in year one even though you're paying over five. A true lease is different: you deduct the payments instead, because you don't own it for tax purposes.
More than 50% business use, and it has to stay that way.
Exactly 50% doesn't qualify. Keep a mileage log. If business use drops below 50% later in the vehicle's class life, part of what you deducted gets recaptured as ordinary income.
"Placed in service" means working, not ordered.
Paying for it, signing for it, or having it on order doesn't count. It has to be delivered, upfitted, and in use in your business by December 31. That's the deadline that actually bites — and it's the reason to have this conversation in September, not the week before Christmas.
One more limit worth knowing: Section 179 can't create a loss. It's capped at your business's net taxable income, and anything you can't use carries forward. Bonus depreciation isn't capped that way — which is one reason the two get used together.
Which vehicles qualify — the three tiers
GVWR is what decides everything, and it's printed on the sticker inside the driver's door jamb.
Dump bodies, service bodies, chassis cabs, anything seating 9+ behind the driver — full deduction, no vehicle-specific cap.
$32,000 Section 179 cap if it's a passenger-type SUV. Remaining basis goes to 100% bonus depreciation. Three ways out of the cap: a cargo area at least 6 feet of interior length not readily accessible from the passenger compartment; seating for more than 9 behind the driver; or a fully enclosed driver compartment with no rear seating and a separate cargo area. That's why a long-bed pickup and a cargo van escape the cap and a three-row SUV doesn't.
§280F luxury-auto limits: $20,300 total first-year depreciation with bonus, $12,300 without. Years two, three, and four-and-after: $19,800 / $11,900 / $7,160.
The New Jersey part nobody mentions
New Jersey does not follow the federal Section 179 number, and a lot of business owners find that out in April.
The $2,560,000 federal limit and 100% bonus depreciation are federal rules. New Jersey decoupled from both. For New Jersey Gross Income Tax — which is what most sole proprietors, partnerships, and S-corp owners actually file — the Section 179 deduction is calculated under the Internal Revenue Code as it stood on December 31, 2002, which caps it at $25,000. New Jersey also disallows the federal bonus depreciation allowance and requires a separate depreciation calculation on the GIT-DEP worksheet. Corporation Business Tax filers have their own adjustment, on Schedule S.
What that means in practice: your federal return and your New Jersey return will show different numbers for the same truck, and the state deduction gets recovered over the following years rather than lost. It's a real consideration in the decision, and it's exactly the kind of thing worth a ten-minute call with your accountant before you sign anything.
The deadline is delivery, not purchase
The deduction is tied to the day the vehicle goes to work, not the day you pay for it. A service body, a ladder rack, shelving, a plow — every one of those adds weeks between the order and the truck actually earning. Commercial inventory tightens every fall for exactly this reason. If a work vehicle is anywhere in your plans this year, the conversation belongs in the fall, not the last week of December.
Start the conversation — 732-264-1600Section 179 vs. bonus depreciation
In practice you take Section 179 first, then bonus depreciation covers what's left. That order is why a heavy SUV can still end up fully expensed in 2026 despite the $32,000 cap. Both are permanent under the 2025 tax law — the year-to-year phase-down schedule businesses planned around for years is gone.
Matt runs the commercial desk in Keyport. He'll pull the GVWR off the door jamb of the exact unit you're looking at, tell you which tier it lands in, and price the upfit before you commit to anything.
"Most people call me in December. The ones who call me in September are the ones who actually get the truck working in time."
Common questions
$2,560,000 in total qualifying business property. The deduction begins phasing out once you place more than $4,090,000 in service and disappears entirely at $6,650,000.
Vehicles used more than 50% for business. Trucks, cargo vans, and vehicles over 14,000 lbs GVWR can be fully expensed. SUVs rated 6,001–14,000 lbs GVWR are capped at $32,000 under Section 179, with 100% bonus depreciation available on the remaining basis. Vehicles at or under 6,000 lbs GVWR are limited by the Section 280F luxury-auto caps.
Yes, when they're used more than 50% for business. Super Duty F-250 and F-350 run roughly 10,000–14,000 lbs GVWR. F-150 runs roughly 6,010–7,850 lbs depending on configuration, and a bed over six feet keeps it out of the heavy-SUV cap. GVWR is on the sticker inside the driver's door jamb, and we'll confirm it on the exact unit before you buy.
$32,000 for SUVs rated between 6,001 and 14,000 lbs GVWR. The remaining basis can still qualify for 100% bonus depreciation, so the cap matters less in 2026 than it did in years when bonus depreciation was phasing down.
Yes. The vehicle has to be new to your business and bought from an unrelated party — it doesn't have to be new off the truck.
Yes. Financing doesn't change the deduction — you claim the qualifying amount in the year the vehicle is placed in service even though you're paying over the term. A true lease works differently: you deduct the lease payments instead, because you don't own the vehicle for tax purposes.
It means delivered, upfitted, and actually in use in your business. Ordering it, paying for it, or having it on order doesn't count. For the 2026 tax year the vehicle has to be working by December 31, 2026.
No. New Jersey decoupled from federal depreciation. For New Jersey Gross Income Tax the Section 179 deduction is figured under the Internal Revenue Code as of December 31, 2002, which caps it at $25,000, and federal bonus depreciation isn't allowed — a separate calculation is required on the GIT-DEP worksheet. Corporation Business Tax filers make their own adjustment. Your federal and New Jersey returns will not show the same number.
Section 179 is a deduction, not a credit, so the saving is the deduction times your combined tax rate. A $75,000 work truck used 100% for business, at an assumed 35% combined rate, is about $26,250 in tax — an effective cost around $48,750. Your real number depends on your entity, income, and state filing.
Part of what you deducted gets recaptured as ordinary income. The rule applies over the vehicle's class life, not just the first year, which is why a mileage log matters.